Reputation is an intangible asset—and, until 2007, a poorly measured one. Equity arbitrage and parametric insurance are just two of the was Steel City Re’s reputation metrics give investors, financial operators, risk professionals, and governance leaders a rigorous lens on this risk factor. We translate an elusive variable into a decision-useful signal giving rise to the reputation value asset class.
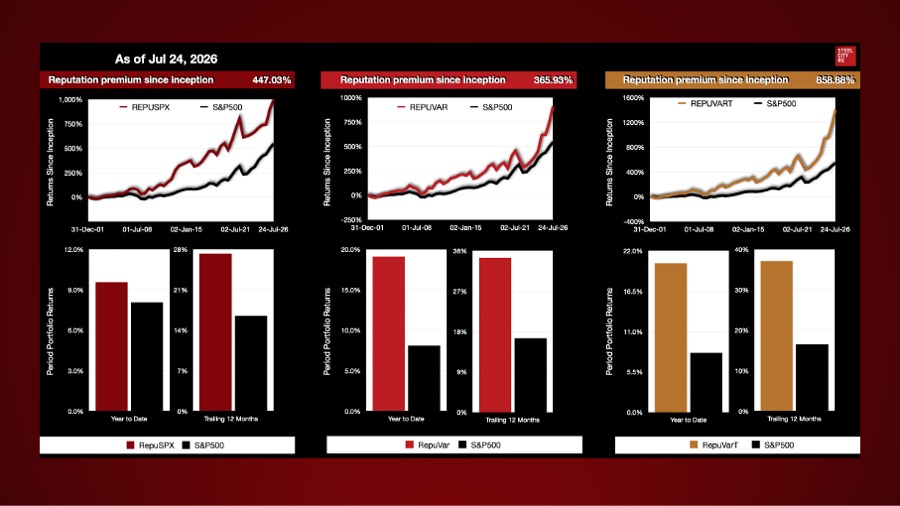
The metrics speak softly–all three reputation arbitrage-based indices are outperforming the S&P500 this calendar year. Lifetime out-performance spreads range between 366% and 859%. RepuSPX, a reputation arbitrage strategy limited to constituents of the S&P500, is at an all time high lifetime spread of 447%.
The trailing twelve month spreads over the S&P500 of the three reputation-linked indices comprising RepuStars Variety Corporate Reputation Composite Equity Index family range from 10.76 to 20.61%. The spread between the two reputation-based price-only indices, REPUVAR and REPUSPX, is down to 7.17% to the disadvantage of RepuSPX.
Steel City Re has a proprietary method for quantifying reputation value. Steel City Re’s reputation metrics enable effective risk management and dutiful governance over mission-critical intangible assets. Like financial reports, the Steel City Re Resilience Monitor helps boards oversee reputation value and risk. They help risk managers mitigate, finance, and transfer risk. The metrics also underpin insurance, including Steel City Re’s new Side R® D&O parametric reputation insurance.
When combined with issues data, as in the Reputation Forecast product by We. Communications, they help communications professionals anticipate, identify, and manage crises. When the regular monitoring of the metrics and issues data are integrated with risk governance and crisis communications preparedness, all over a Side R D&O parametric reputation insurance safety net, the package comprises a comprehensive reputation resilience solution for boards and, by extension, a governance enhancement program for firms.
RepuSPX is limited to constituents of the S&P500 only. RepuVAR is open to all US market-traded companies, including non US-domiciled and ADRs, with market capitalizations greater than $1B. Both portfolios are constructed algorithmically; the latter is calculated by S&P/Dow Jones Indices.
The RepuSPX portfolio was refreshed at the market’s opening January 5, 2026. The RepuStars portfolio was refreshed at the market’s opening January 20, 2026.
An updated detailed analysis of the 24-year performance of RepuSPX and its ability to capture latent reputation value through 2025 (as of Dec 26, 2025) can be found through this link.